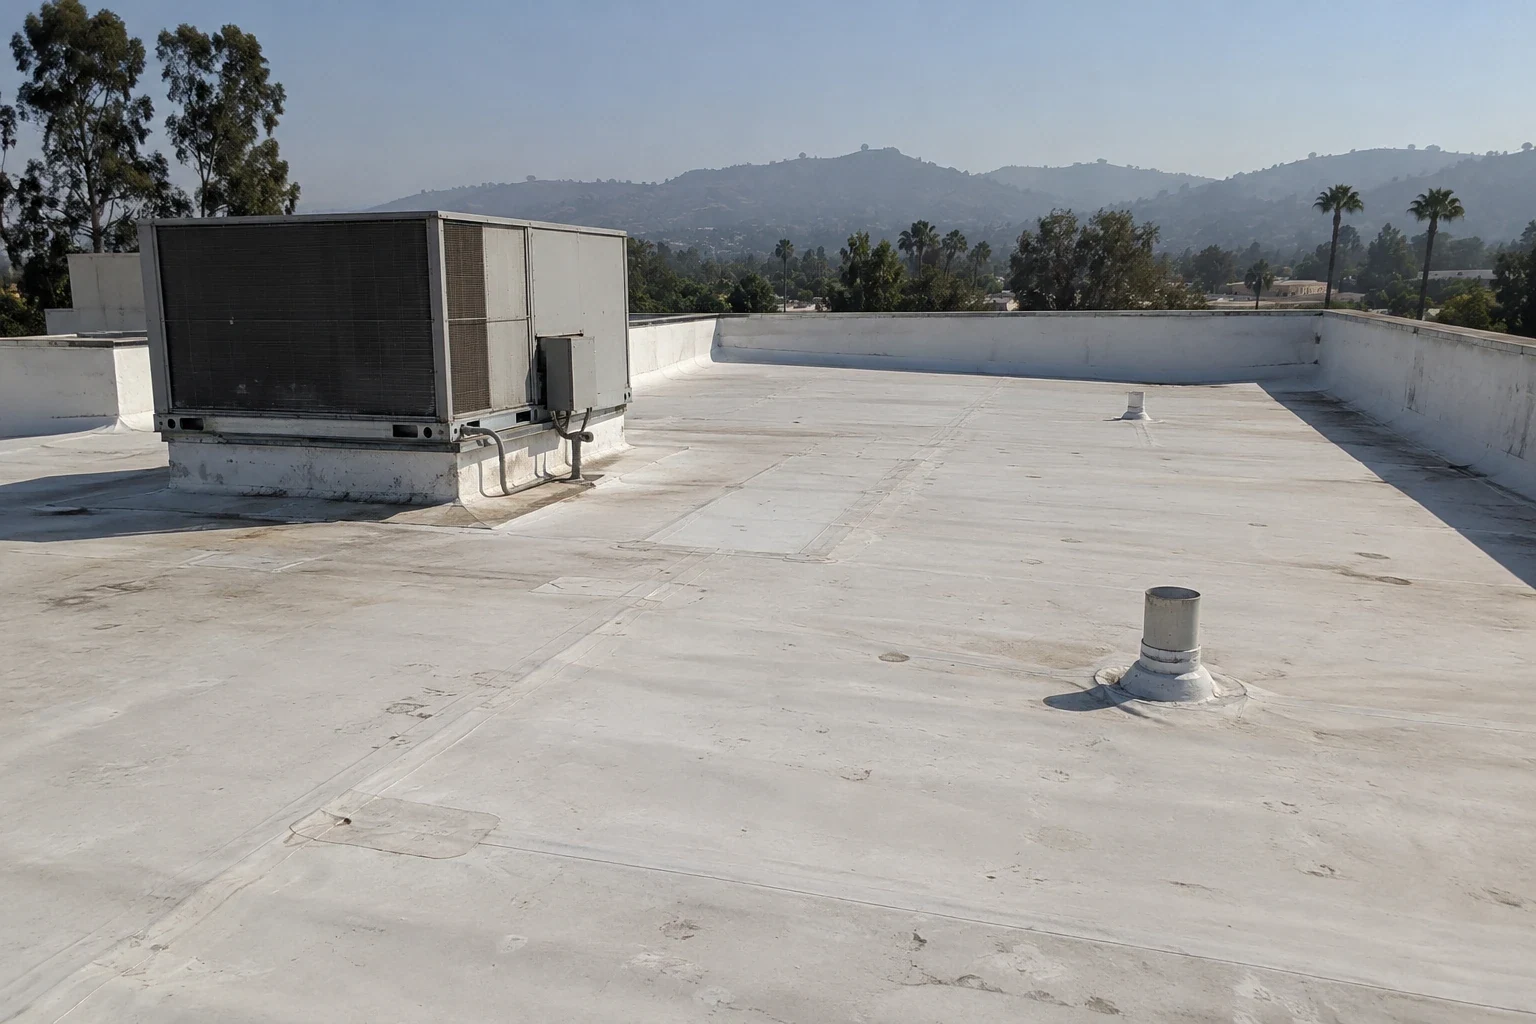
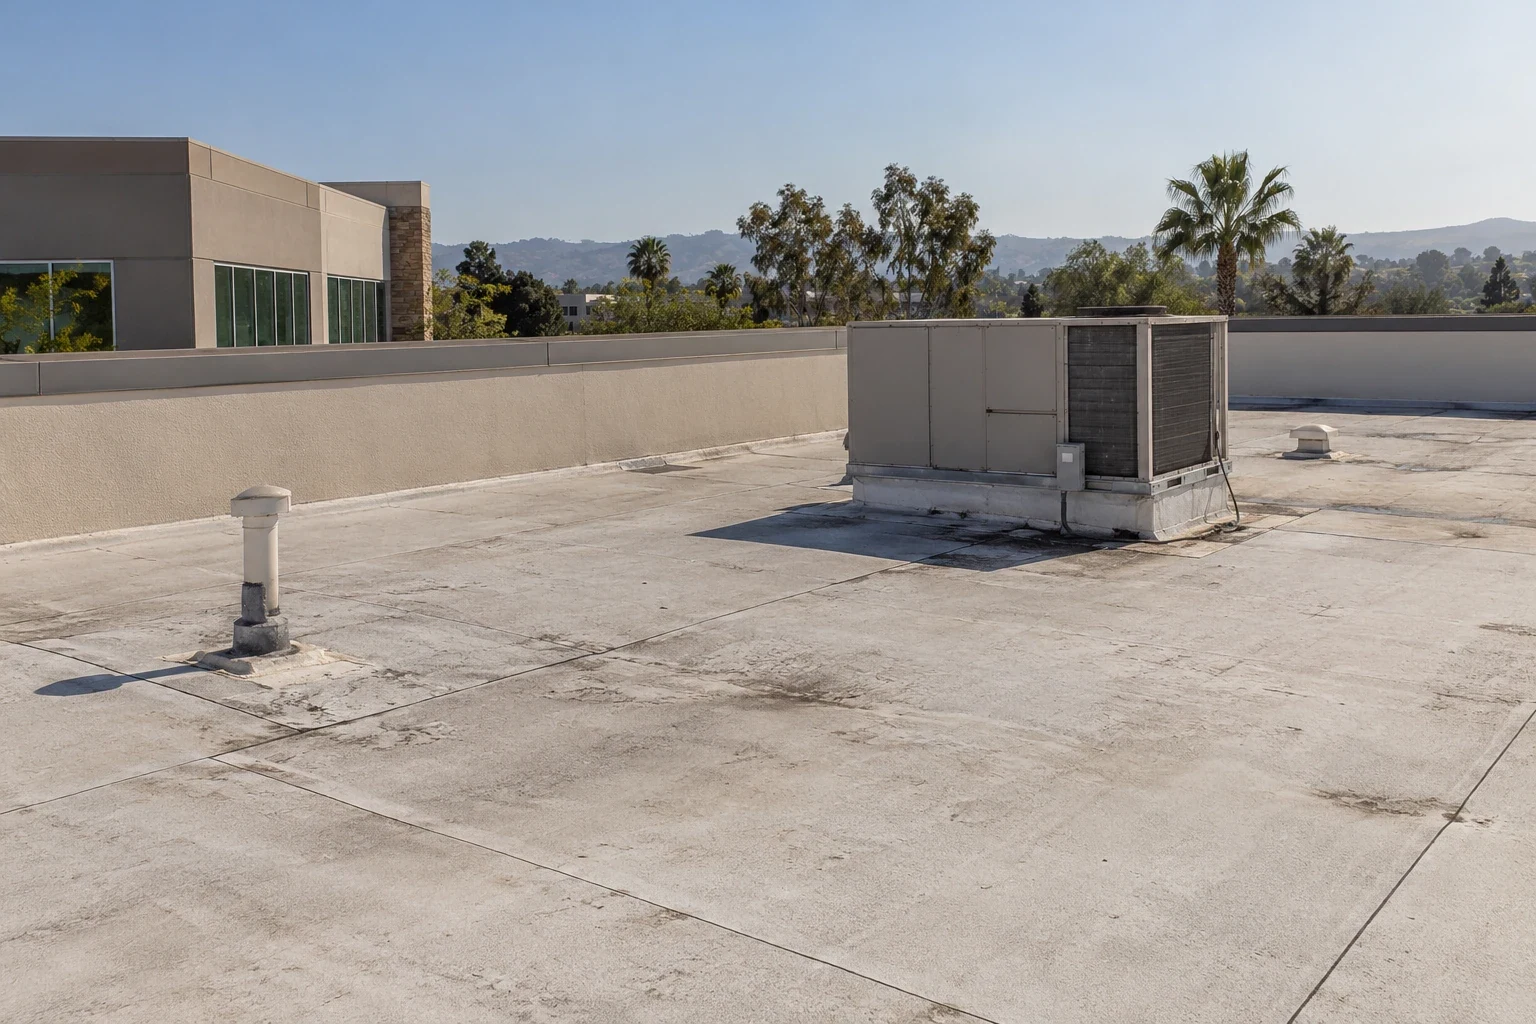
After roof damage in Temecula, the first job is protecting the building, and the claim needs its own clear record of what happened to the roof. Roof insurance claim assistance in Temecula, CA, gives you roof photos, measured repair quantities and a plain account of the damage we could reach, to use in your discussion with the insurer. We keep that roofing help separate from interpreting your policy, negotiating a settlement or assuming a payment. A warehouse roof damage repair scope should show which roof parts need repair, which details we could not inspect and how temporary protection is kept separate from permanent work. For a commercial property near Temecula Valley Wine Country, the claim file should name the damaged roof section, the date we inspected and what we saw, without claiming a cause we cannot confirm. Photos and measured repair items help you discuss the damage with your insurer. Coverage decisions belong to the policy and the carrier, but the repair scope should still describe the work needed to protect and restore the building.
Our first report separates what you told us happened from what we could actually see on the roof. Each photo is tagged with its location and direction, and damaged flashing, lifted edges or interior stains are described plainly. We can record a split seam without claiming we know what caused it, especially where old repairs or hidden layers make the cause unclear. A roof inspection after the damage sets those limits before an estimate treats the whole roof as damaged.
Dates and descriptions matter because temporary repairs can change what the roof looks like when the adjuster arrives. We take photos before and after any approved repair when it is safe, and keep your account separate from what we observed directly. That preserves useful evidence while still letting needed protection go ahead. The report also lists areas we could not reach, since a detail hidden under equipment or a buried layer is still an open question, not proof that there is no damage.
An open roof detail may need temporary protection, with your approval, before a permanent repair is chosen. The estimate should keep that temporary work separate from tear-off, insulation replacement and full flashing repairs, with the location and materials listed next to the cost. Protecting an active roof leak needs safe access and a follow-up plan; a tarp or temporary patch does not settle what the final roof should be or answer an insurance question.
We tie your approval and the temporary work to the damaged area, so later permanent proposals do not count the same work twice. If we find a clogged drain, an old worn repair or an unrelated HVAC leak, we list it separately instead of rolling every problem into the damage claim. Keeping emergency protection, storm-related damage and other repairs apart lets you and the insurer discuss the actual records rather than one unexplained total.
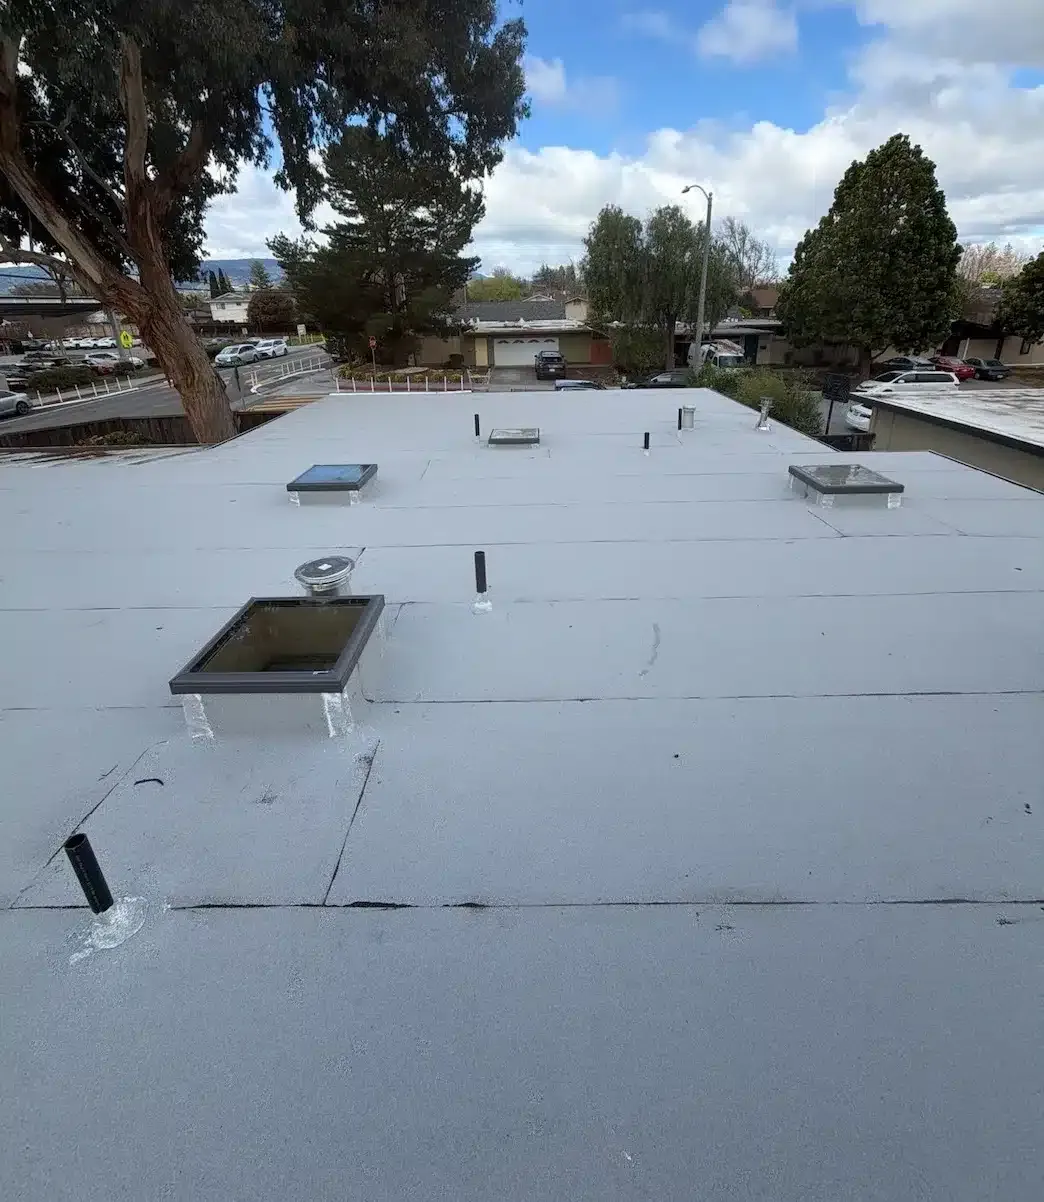
A useful permanent estimate connects each proposed quantity to a roof condition and a complete construction boundary. Membrane removal should identify the affected section, supporting replacement should depend on what is confirmed unsuitable, and flashing reconstruction should identify the interfaces that must be completed together. A TPO repair assembly comparison needs the selected material and compatible connection requirements considered without assuming that any similar-looking sheet can finish the existing roof.
Supporting findings can change quantities after opening, so retain the allowance or authorization method for concealed work rather than presenting an unexamined backing measurement as settled. The estimate should explain associated equipment movement, debris handling and protective closure where those tasks are necessary to complete the correction. These details support construction review because the owner can see why a particular expense belongs to the repair. They do not establish that a policy covers the expense, and any requested coverage explanation should go to the insurer or the owner’s appropriate insurance representative.
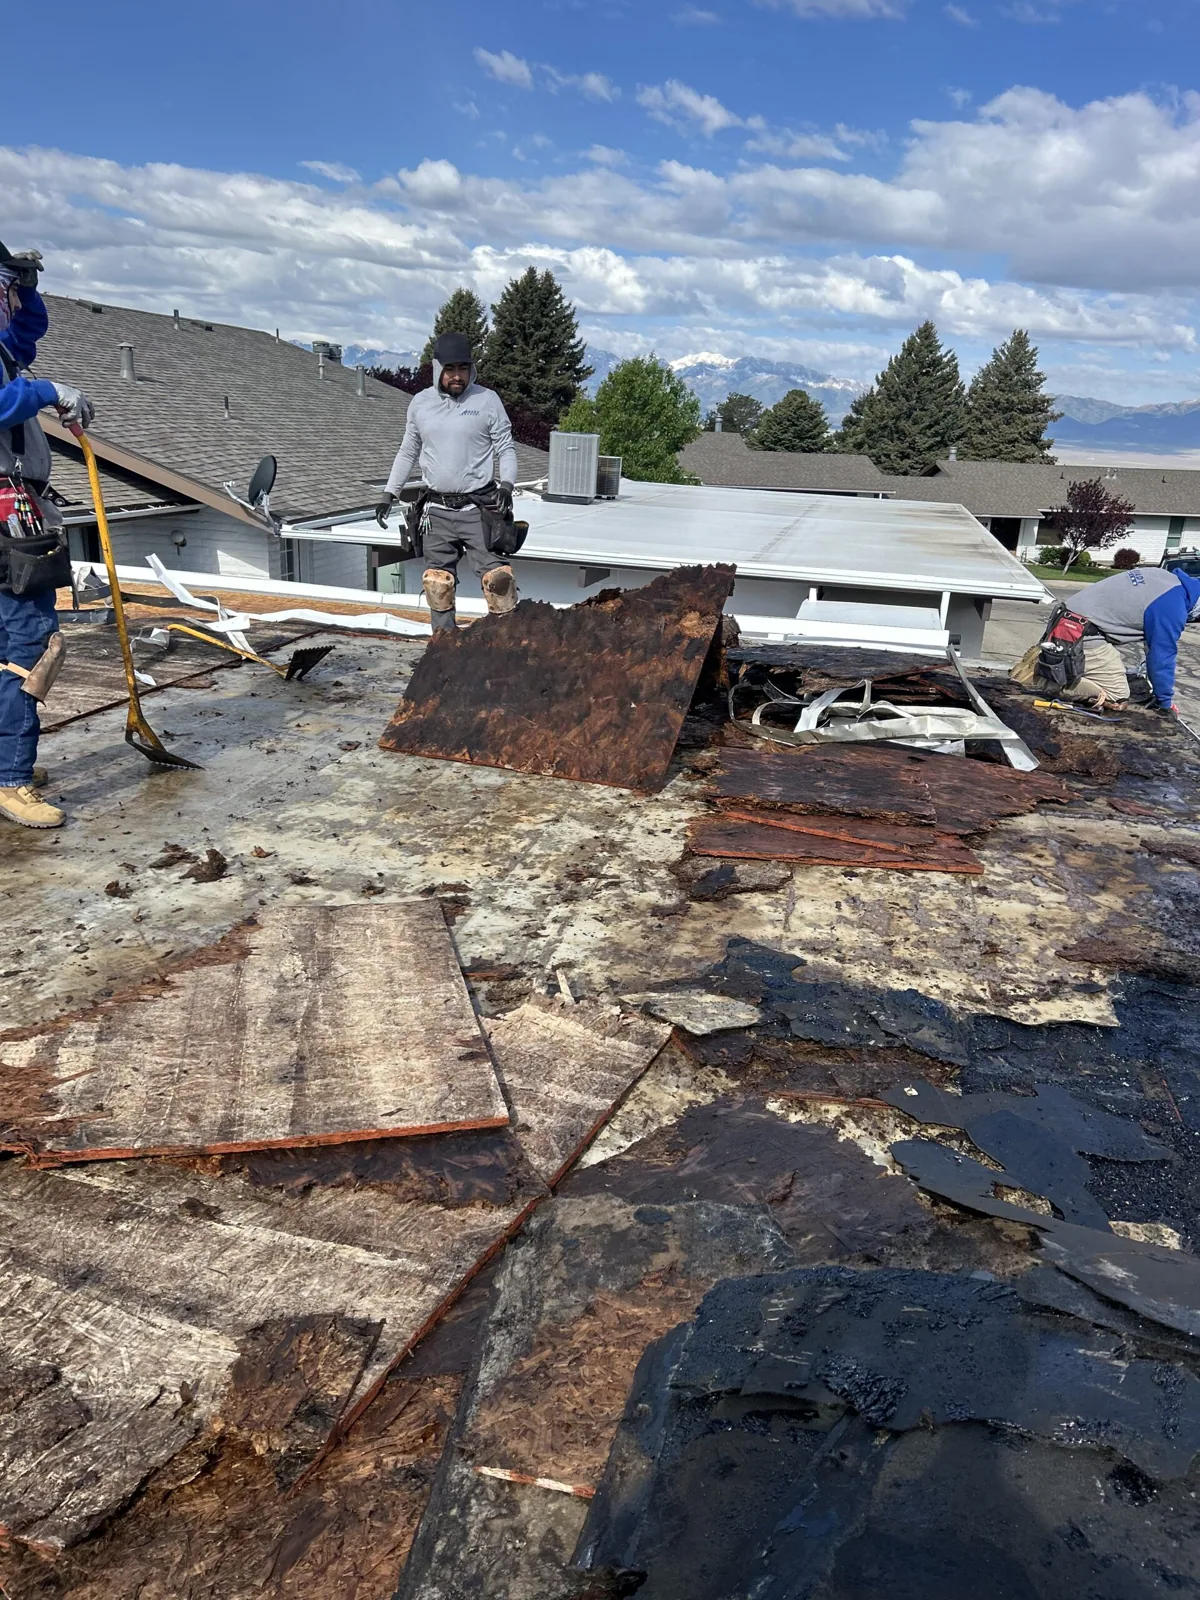
For a useful review, organize the estimate in a way that lets the owner follow each condition to its proposed permanent correction. Separate measured removal, supporting replacement, membrane installation, detail reconstruction and temporary protection instead of folding them into one broad allowance. Note whether a quantity was directly measured, estimated from accessible evidence or held for confirmation after opening the assembly. When a contractor discovers a different condition, preserve the original observation and add the new evidence as a dated change; this keeps the construction record understandable without presenting a scope opinion as a coverage decision.
Repair planning has to respect the building's limits on disruption, especially when damaged roof details sit over sensitive rooms or equipment. You should tell us who can shut down that equipment, where materials can be staged and how an open section will be protected if hidden damage changes the work. Medical office roof damage repairs need those steps planned, rather than assuming an adjuster's visit means every detail can be reached.
Compare repair options over the same damaged area and building limits, and keep any optional upgrade separate from the repair needed to fix the damage. Summer heat may influence your choice of roof surface and when work can happen, but it says nothing about what caused the damage and does not make an upgrade covered. That way you can weigh temporary protection, the permanent repair and optional improvements as separate decisions, while the insurer works through its own policy obligations.
For a Temecula roof loss, identify the affected roof connection and designated operating contact before observations or proposed corrections are assigned. Work around Old Town Temecula commercial roof loss requests likewise needs the particular roof and observed condition attached to the estimate, so a nearby building does not inherit another property’s findings or expense assumptions.
The completed construction account should preserve the affected boundary, actual protective tasks, authorized permanent correction and any unresolved areas requiring another inspection. Retain changed quantities with the supporting findings that explain them, along with photographs showing the finished connection where accessible. If the insurer requests clarification, roof construction records can help answer the physical scope question without promising a claim outcome. The owner keeps a usable repair account for later maintenance and alterations as well as the current discussion, while policy interpretation and the payment decision remain with the responsible insurance parties.
Ask for photos of the damage, a clear outline of the damaged area and quantities tied to a complete permanent repair. Keep temporary protection and optional upgrades separate, and check with your insurer or agent about what the policy covers before counting on reimbursement.
No. A repair estimate describes the work needed for the conditions we found. We keep what you reported separate from what we observed, and recommend further review where hidden layers or old repairs leave the cause unclear, instead of calling every problem storm damage.
We record the newly exposed damage and the change in quantity, get your approval and keep the roof sealed in the meantime. That gives the repair a clear basis and gives your insurer the added records to review under your policy.
Damage photos, a measured repair scope and plain explanations of the work needed. Policy interpretation, settlement and payment decisions belong to your insurer or your own insurance representative; our roof documentation does not replace them.
Send us what you are seeing on the roof, any photos you have and the building's operating limits. We will inspect what we can reach and give you a repair scope that separates needed work from open questions.
Request a Roof Assessment